
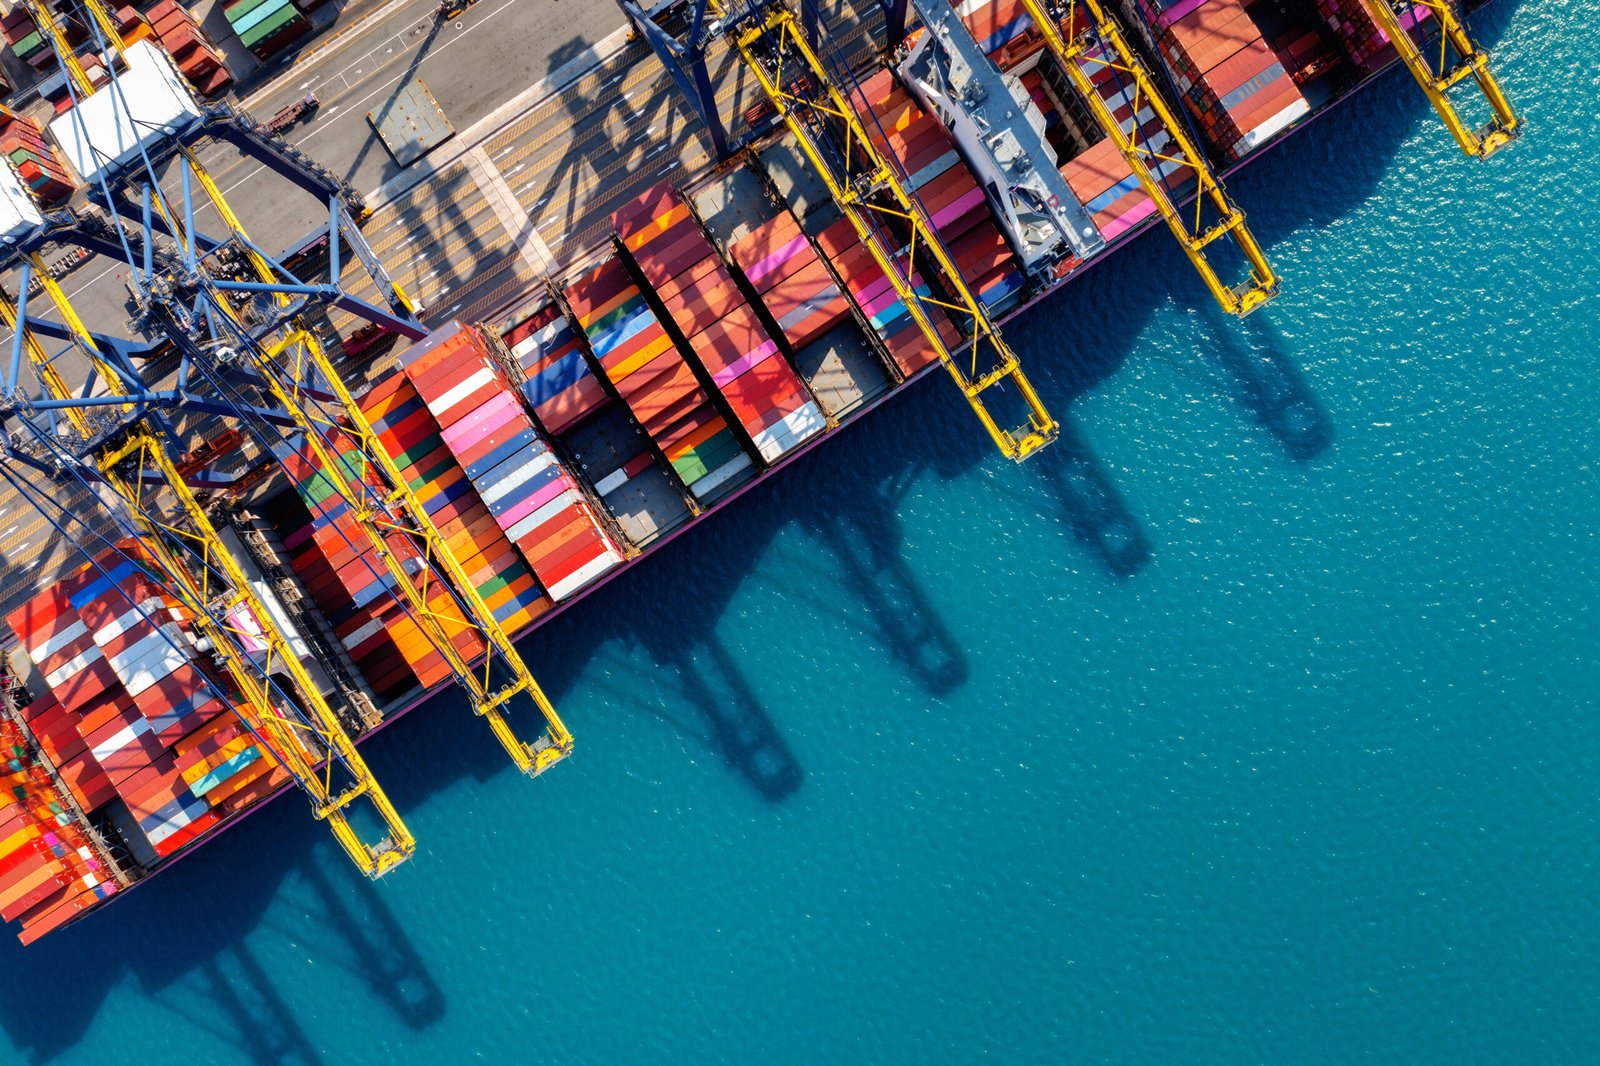
A ship catches fire off Sri Lanka, or a stack of containers goes over the side in heavy weather, and one of them is yours. Most founders assume the carrier pays for that, because the carrier lost the goods.
The carrier does pay. Under US law it pays $500 per package, and that number has nothing to do with what your goods are worth. Cargo insurance is the difference between those two amounts, and the reason experienced importers treat it as a line item rather than an upsell.
The gap is bigger than almost anyone expects, and it is not the only one. There is also a scenario where your goods arrive in perfect condition and you still get an invoice for thousands of dollars, which we get to below.
This is written for founders and brands importing a physical product, not for shippers who already run a claims process. If you have not built out the full cost of the order yet, read this alongside the real cost of importing from China. The premium belongs on that list, and the uninsured loss belongs in your risk model.
What does your carrier actually owe you?
Far less than the value of your shipment, and the cap is written into law rather than into your quote.
The US Carriage of Goods by Sea Act limits an ocean carrier’s liability to $500 per package unless you declared a higher value on the bill of lading and paid the higher freight rate that goes with it. Almost nobody declares value, because the cost of doing so is steep and the option is buried in the terms.
Say you ship goods worth $60,000 in 100 cartons. If each carton counts as a package, the carrier’s maximum exposure is $50,000, which is already less than you lost. The insurance exists to cover the part the statute does not.
The word “package” is doing more work than you think
Here is where it gets sharper, and it moved recently. Carriers have been arguing that the “package” is not the carton but the pallet, and US courts have started to let them.
In March 2026 the Second Circuit held that a carrier can define a package as a palletized unit rather than an individual carton. The definition has to sit in the incorporated terms and conditions and identify genuine packages. A month later, in April 2026, a New York trial court applied that framework but refused to grant it automatically, holding that the record had not settled whether palletizing was done for the merchant’s own convenience.
Run the same shipment through both readings. Those 100 cartons worth $60,000, stacked on 10 pallets, cap the carrier at $50,000 on the carton reading and at $5,000 on the pallet reading.
Same ship, same loss, same paperwork, and a ten-fold difference in what you can recover. That is the exposure cargo insurance is actually buying out.
If your shipment is not governed by US law
Where the Hague-Visby Rules apply instead, the limit is 666.67 SDR per package or 2 SDR per kilogram of gross weight, and the higher of the two applies. In dollars that is roughly $900 a package or under $3 a kilogram.
For air freight the Montreal Convention governs, and the cargo limit rose to 26 SDR per kilogram on 28 December 2024, which is about $35 a kilogram. A 40 kilogram carton of electronics is capped near $1,400 regardless of what is inside it.
Notice what all three rules have in common. They are indexed to weight or to a count of boxes, never to the value of what you are shipping. So the denser and cheaper your product, the better the cap treats you. The lighter and more valuable it is, the worse.
The bill that arrives when nothing happened to your goods
This is the part almost no first-time importer sees coming, and it is the strongest argument for cargo insurance on the page.
It is called general average, and it is one of the oldest rules in shipping. When a vessel is in peril and the crew sacrifices cargo or the owner incurs extraordinary expense to save the voyage, the loss is shared by everyone with goods on that ship, in proportion to the value of their cargo. Your container does not need to be touched. It only needs to be aboard.
Once general average is declared, your goods are not released until security is posted. If you are uninsured, that means a cash deposit, a bank guarantee, or a bond, paid by you, before you see a single unit. If you are insured, your underwriter posts it and your cargo moves.
This is not a historical curiosity. The Ever Given grounded in the Suez Canal on 23 March 2021 and general average was declared, with the vessel held for roughly three months while liability was argued. After the Dali brought down the Francis Scott Key Bridge in Baltimore on 26 March 2024, its owner declared general average on 17 April, three weeks later. Investigators counted 4,680 containers on board the Dali, and the owner of every one of those boxes was drawn in.
Every brand on those ships whose goods were fine still had to find security money before their cargo moved. For a young brand that timing is worse than the amount, because the cash goes out at exactly the moment the inventory is not selling.
Which cover are you actually buying?
Not all cargo insurance is the same cover, and the distinction is where the surprises live.
Marine cargo policies are usually written on the Institute Cargo Clauses. Clause A is the broadest, close to all risks. Clause B and Clause C are named-perils cover, which means they pay only for things on a list, and Clause C is the narrowest of the three. A Clause C policy can be perfectly valid and still decline the thing that actually happened to your container.
Now connect that to your Incoterms, because this is the trap. Under Incoterms 2020, a seller selling on CIP must insure at Clause A level, while a seller selling on CIF only has to provide Clause C, the minimum. Both are set at 110% of the contract price, in the contract currency.
So a CIF quote can arrive with the word “insurance” in the name and still leave you on narrow named-perils cover you never chose. If your supplier is quoting CIF, ask which clause and ask for the certificate, and decide whether you want to buy your own cover on top. The same logic sits behind FOB vs DDP: a term that bundles a service hides the specification of that service.
When is cargo insurance not worth it?
Sometimes it genuinely is not, and any honest answer has to include that.
On a small courier or air parcel of low-value samples, the premium plus the deductible plus the time to file can exceed what you would recover. If the goods are cheap to replace and the delay would not hurt you, self-insuring a first sample run is a defensible choice.
The calculation changes fast, though, and on two triggers rather than one. The obvious trigger is value, because once a shipment represents real money the cap on carrier liability becomes the whole story.
The less obvious trigger is general average, which does not care how small your shipment is. A modest container on a big ship can still be asked for security, and that exposure exists from the first ocean shipment you ever make, not from the point where your orders get large.
The documents that decide your claim
A claim is usually won or lost in the first two days, and mostly on paperwork you either created at the right moment or did not.
Note the damage on the delivery receipt at the moment of delivery, before you sign it, and photograph the container seal, the container number, and the load as you open it. If the damage only shows up when you unpack, put it in writing to the carrier immediately. Keep the timing tight, because the window for concealed damage is set by your bill of lading and the rules governing the shipment.
Then assemble the file. The commercial invoice, the packing list, the bill of lading or air waybill, the insurance certificate, the photographs, any survey report, your written notice to the carrier, and a clear calculation of the loss.
Hold one date above all the others. Under COGSA, a cargo claim carries a one-year statute of limitations to bring suit, and that year runs whether or not the carrier is still politely answering your emails. Friendly correspondence is not an extension, and a claim that quietly ages past the anniversary is simply gone.
The part a partner should be doing for you
Most of this is knowable and none of it is complicated, but it is all invisible until something goes wrong, which is exactly when you do not want to be learning it.
That is one of the practical differences between an operator and a middleman. A middleman forwards you the carrier’s claim form. An operator checks the insurance certificate before the goods sail and confirms which clause you are actually on. It makes sure the declared value and the packing list match what is really in the container, and gets the survey booked while the evidence is still on your dock.
It also matters how that partner is paid. Plenty of agents earn a commission on the freight and insurance they arrange, which quietly makes the sale their priority rather than your cover. At Helix the fee comes from you and we take zero commissions from suppliers, so the advice on whether you need Clause A is just advice.
What to keep from this
Four things, if you remember nothing else.
The ocean carrier owes $500 per package, and recent US decisions mean a package may be a whole pallet rather than a carton, which can cut your recovery by a factor of ten on identical goods. General average can bill you even when your cargo is untouched, and an uninsured importer has to post security in cash before the container is released. A CIF quote buys you the narrowest cover in the Institute Cargo Clauses, while CIP buys the broadest, so ask which clause you are on. And under COGSA the clock on a cargo claim runs for one year, no matter how friendly the correspondence looks.
Let us check the cover before your goods sail
We have launched 18 brands and verified 800+ suppliers, with our own team on the ground in China. Before a container moves we confirm the insurance certificate and the clause behind it, check the declared value against the packing list, and make sure the paperwork will survive a claim rather than fall apart in one.
Tell us what you are shipping, and we will tell you straight where your exposure actually sits.
Frequently asked questions
Does the shipping carrier cover my cargo if it is lost or damaged?
Only up to a legal cap, and the cap is not tied to the value of your goods. Under the US Carriage of Goods by Sea Act an ocean carrier’s liability is limited to $500 per package unless you declared a higher value and paid for it. Where the Hague-Visby Rules apply, the limit is 666.67 SDR per package or 2 SDR per kilogram, whichever is higher. For air freight, the Montreal Convention limit has been 26 SDR per kilogram since 28 December 2024, and cargo insurance covers the gap between those caps and what your shipment is actually worth.
What is general average, and can it affect me if my cargo is fine?
Yes, and that is the point of it. General average is a shipping rule under which every cargo owner on a vessel contributes to the loss when cargo is sacrificed or extraordinary costs are incurred to save the voyage, in proportion to the value of their goods. Your container can be completely undamaged and still be held until you post security, as a cash deposit, bank guarantee, or bond. If you carry cargo insurance, your underwriter posts that security and the goods are released.
My supplier quoted CIF, so am I already insured?
You have insurance, but probably the narrowest kind. Under Incoterms 2020 a CIF seller only has to provide cover at Institute Cargo Clauses C. That is a named-perils policy which pays for a short list of events, while a CIP seller must provide Clauses A, close to all risks. Both are written at 110% of the contract price, so ask your supplier which clause the certificate is issued on, read what it excludes, and buy your own cover on top if the gap matters to you.